Frugal Family Living

Teaching Kids About Money at Every Age: Frugal Parenting in Practice
Teaching Kids About Money at Every Age: Frugal Parenting in Practice

Photo: latesttrend.net editorial

Financial habits start young. Explore age-appropriate, low-pressure ways to help children understand money without creating anxiety around it.

Key Takeaways

  • Children can grasp basic money concepts as early as age three or four with simple, hands-on tools.
  • Age-appropriate tasks matter more than formal lessons; matching complexity to development prevents frustration.
  • Talking openly about household trade-offs teaches kids that budgeting is normal, not stressful.
  • Giving kids a small amount of money to manage themselves builds real decision-making skills faster than instruction alone.
  • Mistakes with small amounts of money early on are low-cost learning opportunities worth allowing.

Why money conversations start at home

Schools rarely cover personal finance in depth, and when they do, it is often too late to shape the reflexes kids carry into adulthood. The habits children build around money before age ten tend to stick. That does not mean parents need a financial background or a complicated curriculum. It means finding small, natural moments in daily life to let money make sense.

Families who talk openly about spending decisions without shame or anxiety tend to raise children who are less impulsive with money later on. The goal is not to manufacture money lessons but to stop hiding the ordinary financial decisions that happen every week. See everyday habits of consistently frugal families for how small routines compound over time.

Age-by-age practices that actually fit

Different ages need different approaches. Pushing abstract concepts too early creates confusion; waiting too long wastes formative time.

1

Use physical coins and jars with children ages three to six

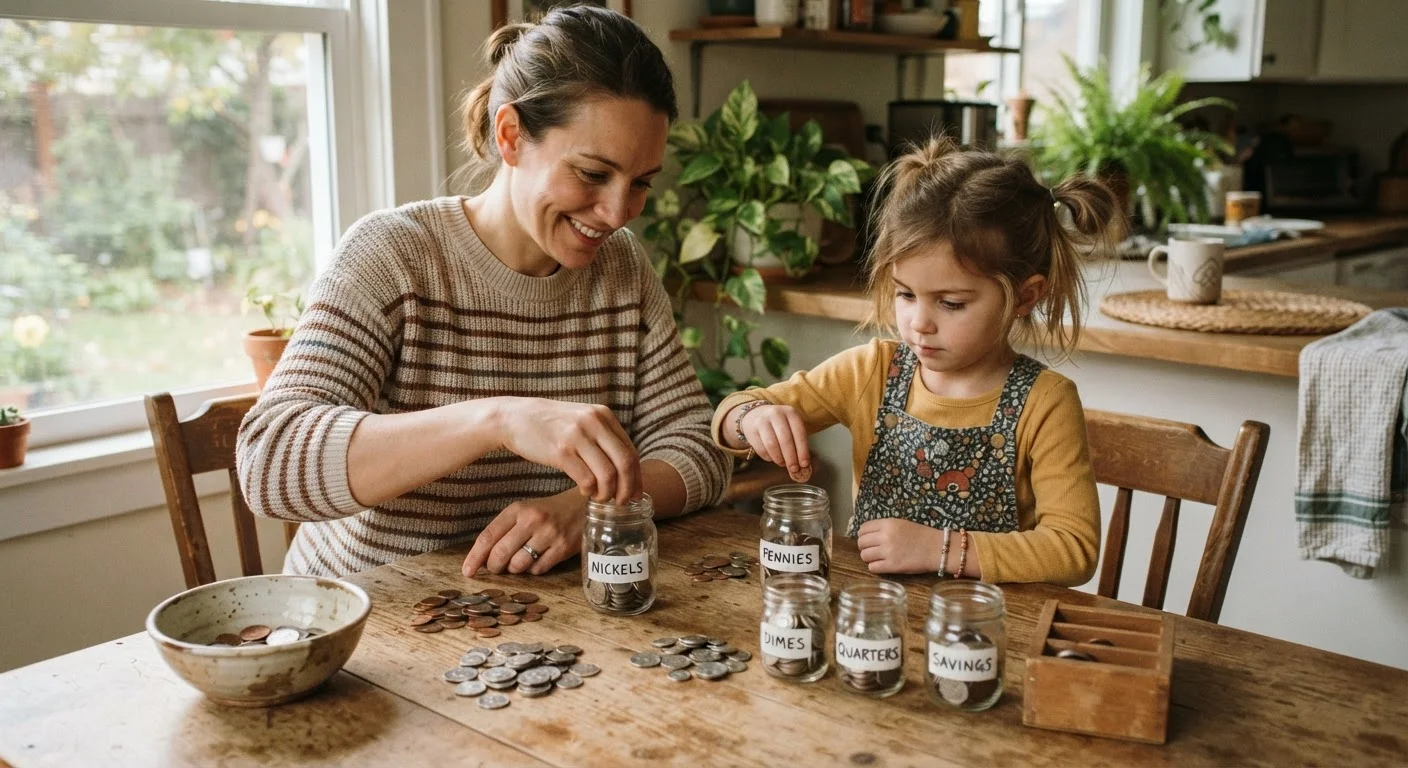
Young children think concretely. Coins they can hold and count are far more real to them than numbers on a screen or a card swipe. Three labeled jars (spend, save, give) give them a simple decision framework without overwhelming choices.
Example: A five-year-old who receives a dollar for helping with chores can drop coins into each jar and immediately see that spending some means having less to save.
2

Let children ages seven to ten make small purchase decisions themselves

Children at this age can understand that money is finite and that choosing one thing means not choosing another. Letting them manage a small weekly or monthly allowance, even a few dollars, builds that understanding through direct experience rather than explanation.
Example: A child given a set amount for a school supply run who chooses a cheaper notebook in order to afford a colored pen set learns trade-offs more durably than from a lecture.
3

Narrate your own spending decisions with preteens

Children ages ten to thirteen are ready to understand that adults weigh options and sometimes say no to things they could technically afford. Hearing a parent say 'We could eat out tonight, but cooking at home saves us about fifteen dollars we can put toward the camping trip' shows budgeting as a normal tool, not a sign of scarcity.
Example: Narrating a grocery store substitution, such as choosing a store-brand product over a name brand to stretch the weekly food budget, gives preteens a concrete look at how small choices add up.
4

Give teenagers a real budget category to manage

Teens learn faster when the stakes are modest but genuine. Handing over responsibility for their own clothing budget or school lunch money for a month puts decision-making in their hands and creates natural conversations when the money runs low.
Example: A fourteen-year-old managing a monthly clothing budget for the first time may overspend in week one, but by month three, most will have learned to pace themselves without any parental lecture.
5

Talk about saving goals in concrete terms, not abstract virtues

Telling a child to 'save for the future' is too vague to motivate action. Tying savings to something specific and visible, like a particular toy, a family outing, or a contribution to a road trip fund, makes the waiting feel purposeful.
Example: A child who can see a progress chart on the refrigerator showing how many more weeks until they reach their savings goal is more likely to resist impulse spending than one given a general instruction to save.

Quick ways to get started this week

None of these changes require a new system or a special trip to the store. Most fit into routines already happening in your household.

high Set up three jars labeled 'spend,' 'save,' and 'give' and introduce them the next time your child receives any money, however small.
medium Narrate one grocery store substitution out loud on your next shopping trip, explaining the dollar difference and what that amount could go toward instead.
medium Hand your child the exact cash for a small errand, such as paying for a loaf of bread, and let them handle the transaction themselves.
high Write a savings goal with your child on a piece of paper, note the target amount, and tape it somewhere visible in your home.

For a broader look at how to structure household finances alongside these conversations, building a weekly family budget that sticks walks through practical steps that work for real households. If you are also looking at how family spending myths shape what you think kids need, separating family spending myths from reality is worth reading alongside this one.

Frugal Family Living Editorial Team

latesttrend.net

Frugal Family Living Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.

Frugal Family Living
View author profile

The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.