A First-Time Homeowner's Guide to Budgeting for Maintenance and Repairs
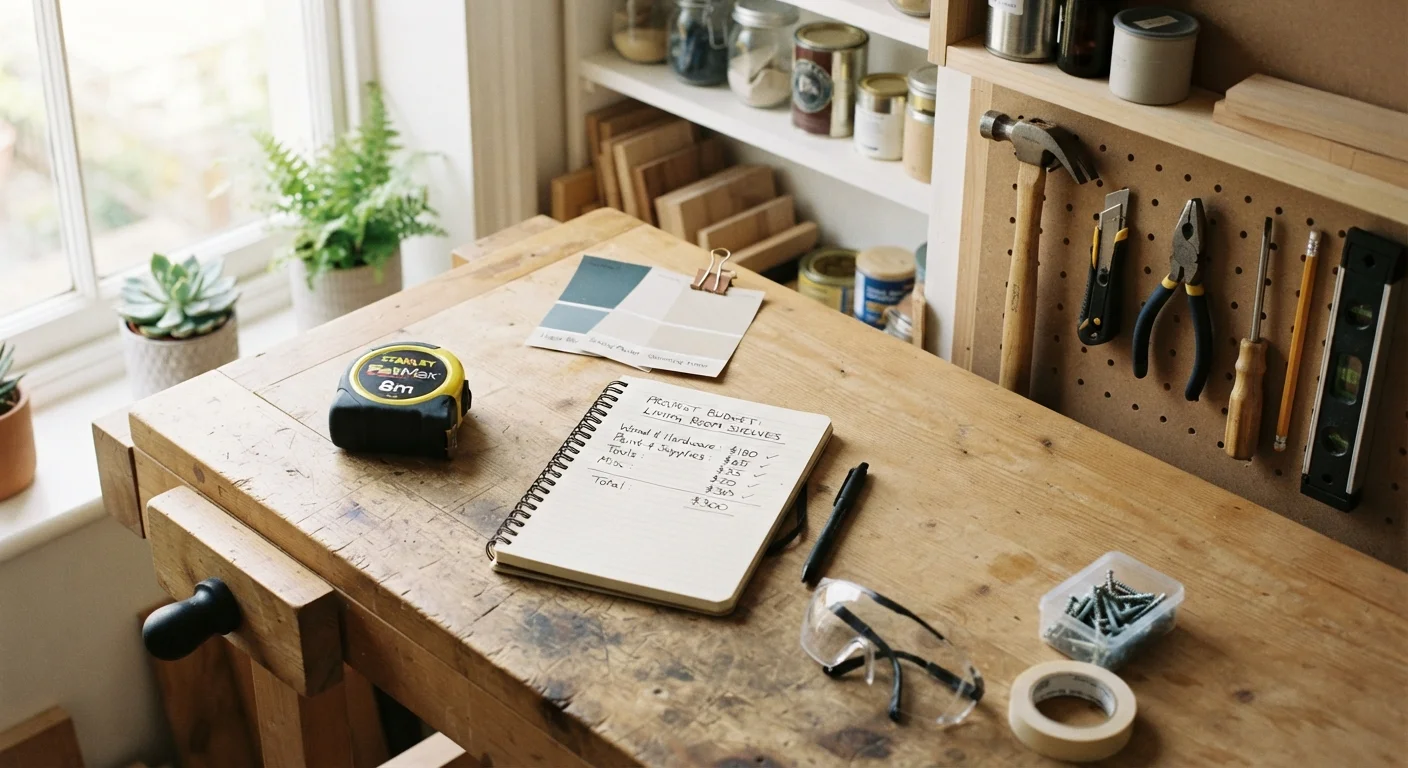
Photo: latesttrend.net editorial
Key Takeaways
- Most first-time homeowners underestimate annual maintenance costs because rental experience does not prepare them for full ownership.
- The widely cited 1% rule is a starting point, not a reliable formula; home age, condition, and location all affect real costs.
- A dedicated savings account for home maintenance, separate from your emergency fund, gives you the most control.
- Preventive tasks done on a schedule cost far less than reactive repairs after something fails.
- Some repairs are worth hiring out even on a tight budget, because DIY mistakes on complex systems can cost more to fix.
Why maintenance budgeting catches first-timers off guard
Renters get used to calling a landlord when something breaks. That habit disappears the moment you own the home. Every leaky faucet, failing furnace, and cracked gutter is now your expense, and the bills arrive without warning if you have not planned for them.
The shift is not just psychological. Homeownership adds a layer of costs that most first-timers simply have not tracked before: routine upkeep, seasonal tasks, gradual system wear, and occasional large replacements. Without a plan, families tend to pull from their general savings or use credit each time something goes wrong, which makes ordinary maintenance feel like a financial emergency.
The goal of a maintenance budget is to make those costs predictable. That does not require a complicated system. It requires knowing roughly what your home needs, setting money aside before the bill arrives, and understanding which spending is truly unavoidable versus which can be managed with a little planning. See our guide to common home maintenance myths for a look at advice that can push families to overspend on upkeep that may not be necessary.
1% rule
A commonly cited guideline suggesting homeowners save roughly 1% of their home's purchase price each year for maintenance. It is a rough starting estimate, not a precise formula.
Deferred maintenance
Upkeep or repairs that were postponed and have accumulated over time. Homes with deferred maintenance often require larger spending shortly after purchase.
Home maintenance fund
A dedicated savings reserve set aside specifically for home upkeep and system replacements, kept separate from a general emergency fund.
Preventive maintenance
Scheduled, low-cost tasks done regularly to keep home systems running and prevent larger failures, such as changing filters or cleaning gutters.
System lifespan
The typical number of years a home system or appliance is expected to function before needing replacement, used to estimate when large costs are likely.
The common rules of thumb, and what they miss
The two figures cited most often are the 1% rule and the square footage rule. The 1% rule says to save 1% of your home's purchase price each year. The square footage rule suggests roughly $1 per square foot annually. Both give you a number to work with, and both have real limitations.
A newer home in good condition may not need anywhere near 1% in early years. An older home with original systems could easily need 2% or more. Purchase price also varies enormously by market: two identical houses in different cities might be priced very differently, meaning the 1% figure produces wildly different budget targets even when the actual maintenance needs are the same.
Neither rule accounts for the age of your roof, whether your HVAC is original, or what a home inspection flagged as deferred maintenance. Those specifics matter far more than purchase price alone. Use the rules as a floor, not a ceiling, and adjust based on what you actually know about your home's systems.
How to build a realistic maintenance fund
Start by listing every major system in your home: roof, HVAC, water heater, electrical panel, plumbing, foundation, windows, and major appliances. For each one, note the approximate age and estimated lifespan. A 12-year-old furnace with a 15 to 20-year lifespan needs a replacement fund now. A 3-year-old roof does not require the same urgency.
Once you have that list, you can estimate a rough annual contribution for each system based on replacement cost divided by remaining useful years. Add those amounts together and you have a more grounded savings target than any percentage rule provides.
Keep this money in a dedicated savings account separate from your emergency fund. Building a weekly family budget that treats the home maintenance contribution as a fixed monthly line item, the same way you treat insurance or utilities, prevents the fund from being raided for other purposes. Even $100 to $200 a month, started early, prevents a single large repair from derailing your finances.
Routine tasks that keep costs predictable
Preventive maintenance is how you avoid the largest bills. A furnace filter changed every one to three months runs a few dollars. A furnace that fails from neglected maintenance can cost thousands to replace. The same logic applies to gutter cleaning, caulking around windows and doors, checking for small roof damage after storms, and testing smoke and carbon monoxide detectors.
These are not glamorous tasks, but they compress your unpredictable repair costs into a smaller range. Our guide to preventive maintenance tasks covers the specific jobs worth putting on a regular schedule. For air sealing work you can handle yourself, this walkthrough on caulking and weatherstripping covers the steps without requiring a contractor.
Deciding what to do yourself and what to hire out
DIY repairs save real money on the right tasks. Swapping out a light fixture, patching drywall, painting, replacing a toilet fill valve, and basic caulking are all within reach for most homeowners willing to follow instructions carefully. The savings on labor can be significant.
Other work warrants a licensed professional. Electrical panel work, gas line repairs, structural modifications, and roof replacements involve safety risks and often require permits and inspections. A mistake on any of these can create hazards or void homeowner's insurance, and the cost to correct a DIY error frequently exceeds what a professional would have charged. If you are unsure which category a task falls into, this comparison of DIY versus hiring out walks through the decision in detail. For tool costs on one-off projects, renting versus buying tools is worth considering before you spend money on equipment you may only use once.
Get a sewer scope inspection if you have not
Frequently Asked Questions
The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.