The Weekly Family Budget: How to Build One That Actually Sticks
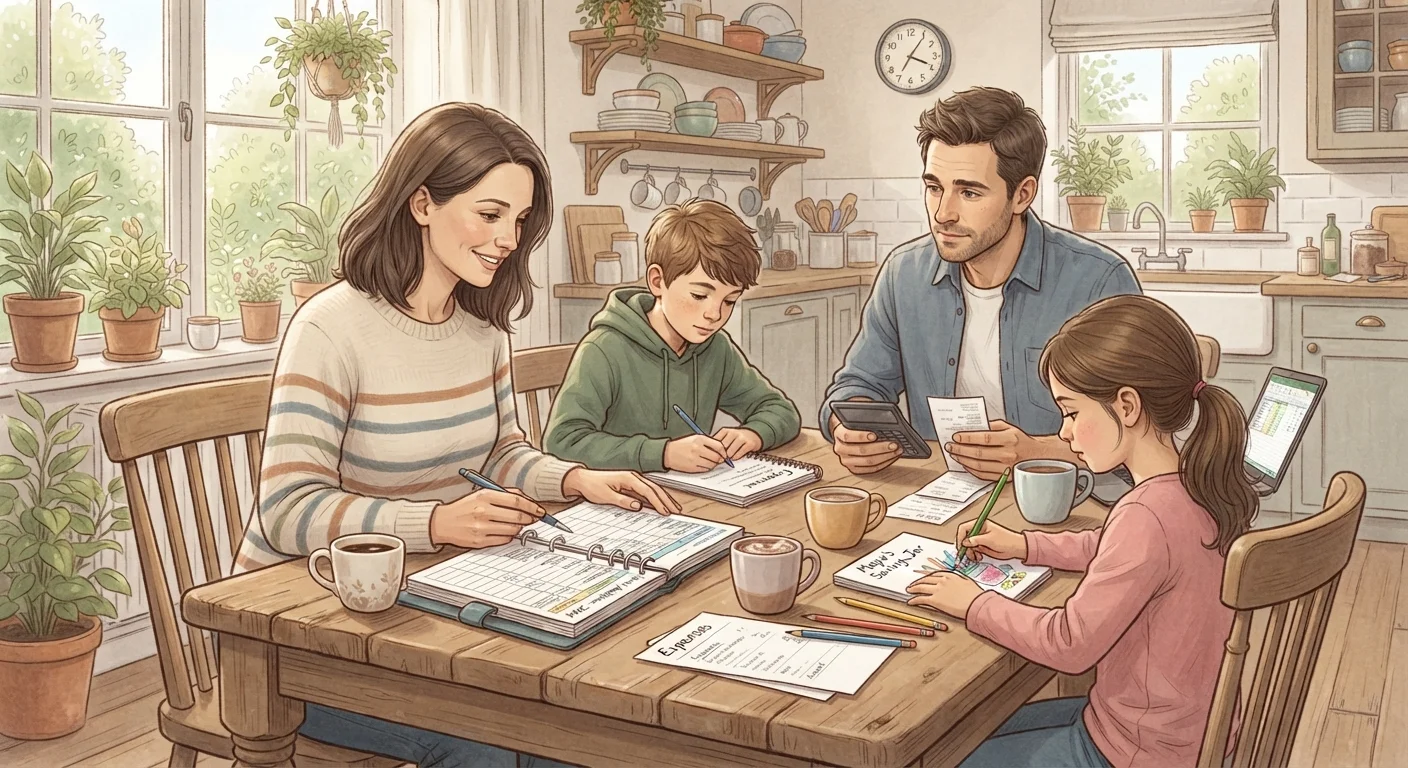
Photo: latesttrend.net editorial
Key Takeaways
- A weekly budget works better than a monthly one for most families because it matches how spending actually happens.
- Knowing your fixed and variable costs separately makes it easier to find room to cut.
- Tracking spending for just one week before setting limits gives you a realistic baseline.
- A small weekly buffer category prevents budget failure when unexpected costs appear.
- Review the budget together as a household so everyone understands the shared limits.
Why weekly beats monthly for most families
Monthly budgets look clean on paper, but most family spending happens in short, irregular bursts: a big grocery run, a week of school lunches, a weekend with extra driving. By the time you notice a monthly budget is off track, three weeks have already passed.
A weekly budget shrinks the feedback loop. You know by Sunday whether the week went sideways, and you have time to adjust before it compounds. It also matches the natural rhythm of most paychecks and most household routines.
If your family tends to overspend on specific categories without realizing it, a weekly structure makes the pattern visible faster. The same principle applies to travel spending, which you can read more about in our look at why families overspend on vacation.
What you will need
What you need before you start
The tools involved are simple. You do not need paid software or a financial background. A printed bank statement and a pencil are enough to complete every step below.
One area worth auditing before you begin: recurring charges. Streaming services, app subscriptions, and membership fees often appear on statements without being noticed. A quick scan can surface charges you have forgotten about. For a more thorough look at this, see our article on how recurring charges quietly reshape family budgets.
Bank or credit card statements (2 to 4 weeks)
Used to identify actual spending patterns before setting category limits.
Notebook or free spreadsheet
Used to record income, fixed costs, and category spending each week.
Free budgeting app
Optional tool for tracking daily purchases automatically if you prefer digital records.
Calculator (phone calculator is fine)
Used to convert monthly bills to weekly amounts and total categories.
Once you have these ready, the steps below walk you through building the budget from income down to category limits.
Add up your weekly take-home income
Start with what actually lands in your bank account each week after taxes, not your gross salary. If you are paid biweekly, divide your net paycheck by two. If income varies week to week (gig work, tips, hourly shifts), use the lowest typical amount you receive, not the best week you can remember.
If your household has more than one earner, add both after-tax amounts together. Write this single number at the top of your page. Everything else you build depends on it.
List your fixed weekly obligations
Fixed costs are amounts that stay the same regardless of what you do that week. Convert monthly bills to weekly amounts by dividing by 4.3. Common examples include rent or mortgage, car payments, insurance premiums, and any loan minimums.
Do not include subscriptions here yet. Write each fixed item and its weekly dollar equivalent, then total them. Subtract that total from your weekly income. The remaining number is your spendable income for the week.
Track all variable spending for one real week
Before you set any limits, spend one week writing down every purchase: groceries, gas, coffee, kids' activities, fast food, parking, everything. Use your bank app, a small notebook, or a free budgeting app. Do not change your behavior yet; just observe it.
At the end of the week, group your spending into categories: food at home, food away from home, transportation, children, entertainment, household supplies, and subscriptions. Total each category. This is your baseline.
Set a realistic spending limit for each category
Using your baseline from Step 3, decide which categories have obvious room to shrink and which ones are already tight. Set a weekly dollar target for each variable category. Your targets must total less than your spendable income from Step 2.
A category-by-category approach is more useful than a single lump-sum limit, because it tells you where you actually went over at the end of the week. For food planning ideas that can reduce your grocery category, see the meal planning guide for families.
Add a small weekly buffer
Reserve a specific dollar amount each week for costs that were not planned: a school supply request, a co-pay, a birthday card, a parking ticket. Call it whatever you want; the point is that it exists as a named line item in your budget, not as money you silently borrow from another category.
Even $15 to $25 per week in a buffer category can prevent a single unplanned expense from derailing the whole structure. If you do not use it that week, roll it forward or move it to savings.
Review and adjust at the end of each week
Set aside 10 to 15 minutes at the end of every week, same day and time each week, to compare actual spending against your plan. Note where you went over, where you came in under, and whether any category limits need to be adjusted.
The goal is not a perfect score every week. The goal is a clear picture. Over time, the weekly review catches problems before they compound. For broader patterns in how frugal households manage spending, see everyday habits of families who spend less.
Connecting the budget to the rest of family life
A weekly budget works best when it connects to other household systems. Grocery spending, for example, drops reliably when meals are planned in advance. The comparison between bulk buying and weekly shopping can help you decide which approach fits your category limits better.
Home costs are another area where weekly tracking pays off. Families who set aside a small amount each week for maintenance and repairs avoid large, stressful surprises. Our guide to budgeting for home maintenance covers how to size that fund realistically.
A budget that works does not require perfect discipline. It requires enough structure to catch problems early and enough flexibility to survive real life.
The content provided on our blog site traverses numerous categories, offering readers valuable and practical information. Readers can use the editorial team’s research and data to gain more insights into their topics of interest. However, they are requested not to treat the articles as conclusive. The website team cannot be held responsible for differences in data or inaccuracies found across other platforms. Please also note that the site might also miss out on various schemes and offers available that the readers may find more beneficial than the ones we cover.